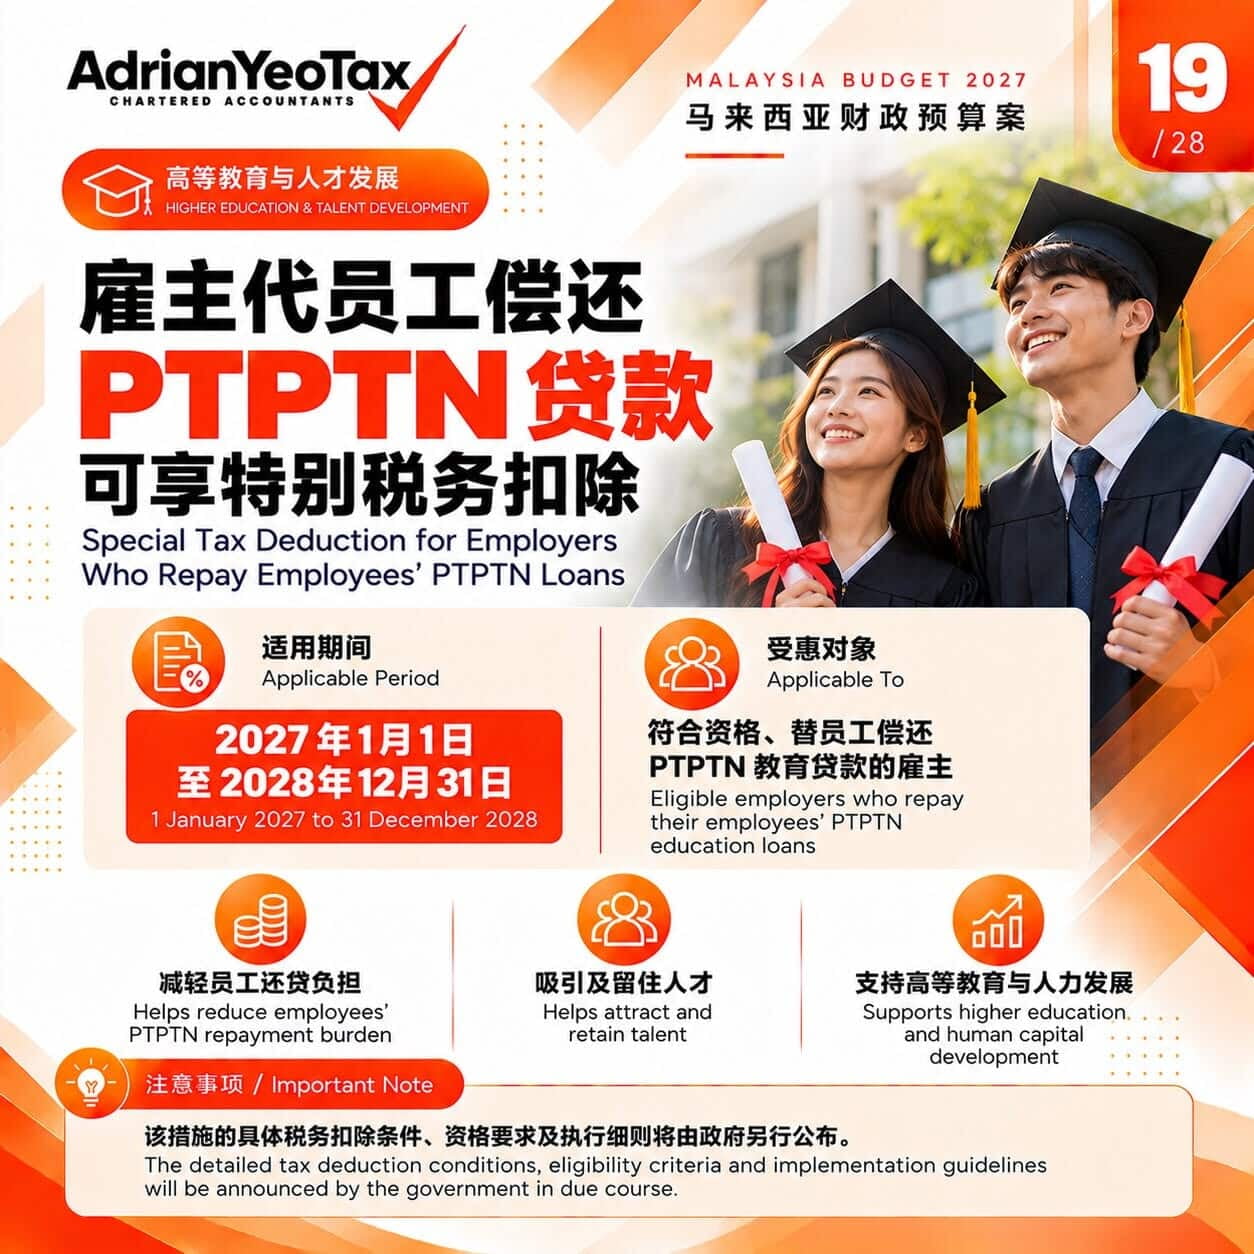
For many young Malaysians, a PTPTN loan is the first big financial obligation of their working lives. Budget 2027 brings in a measure that encourages employers to help: a tax deduction for employers who repay PTPTN loans on behalf of their employees.
What was announced
The government agreed to offer a tax deduction to employers who make PTPTN loan repayments for their employees. The incentive covers repayments made from 1 January 2027 to 31 December 2028, a two-year window.
Reports describe it as applying to companies that settle PTPTN loans on behalf of their full-time employees.
Why it matters
For employers, it is a new way to offer a benefit that employees value, and one that comes with tax relief. For employees, an employer contribution reduces outstanding debt and can lift a real financial weight, particularly for recent graduates. For businesses competing for young talent, it can also be a useful tool for attracting and keeping people.
The wider PTPTN package in Budget 2027
The employer deduction sits within a set of PTPTN measures announced together:
- Deferment of repayments in 2027 for borrowers earning up to RM2,500 a month.
- Minimum repayment of RM50 a month for borrowers earning between RM2,501 and RM3,000.
- 10% discount for borrowers with no arrears who make regular repayments.
More than 400,000 borrowers are expected to benefit from the deferment and minimum repayment measures. Eligibility for the deferment will be based on income information verified with LHDN.
What we do not know yet
Several important details are still to come, and as the slide says, the government will announce the conditions in due course. Points to watch include:
- Deduction treatment. Reports say “tax deduction”. Whether this is an ordinary business deduction or something more generous has not been spelled out.
- Employee treatment. It is not yet clear whether employer repayments will be treated as a taxable benefit for the employee. This matters for both sides.
- Eligibility. Which employees and which employers qualify, and what documents are required, are still to be confirmed.
- Payment mechanics. How payments are made to PTPTN on the employee’s behalf, and how they must be recorded.
An illustration, with caveats
Suppose a company repays RM500 a month towards an employee’s loan during 2027, a total of RM6,000. If it is treated as an ordinary deductible expense, a company paying tax at 24% would reduce its tax by about RM1,440, and an MSME at 16% by about RM960. These are our own illustrative figures, and the actual outcome depends on the final rules.
What employers can do now
- Consider whether you want to offer this benefit. Think about the cost, the number of employees and whether it fits your retention strategy.
- Prepare a policy. Decide which employees would be covered, what limits apply and how the benefit would be documented.
- Wait for the guidance before you commit to a scheme, especially on employee tax treatment.
- Keep clear records of every payment, including PTPTN receipts and employee details.
Speak to AdrianYeo Tax
Employee benefits touch payroll, tax and cost planning all at once. Our chartered accountants can help you design a benefit that works for your business, and keep it compliant.
This article is for general information only and does not constitute tax advice. Measures are based on Budget 2027 announcements and may change when the legislation is finalised. Please consult a tax professional about your specific circumstances.