When a business buys equipment, the tax deduction doesn’t usually come all at once. It is normally spread over several years through capital allowances. For smaller purchases, though, the tax system offers a shortcut: the small value asset allowance, which allows a 100% write-off in the year you buy the asset. Budget 2027 makes this shortcut cover more assets.
What changed
Effective from the 2027 year of assessment:
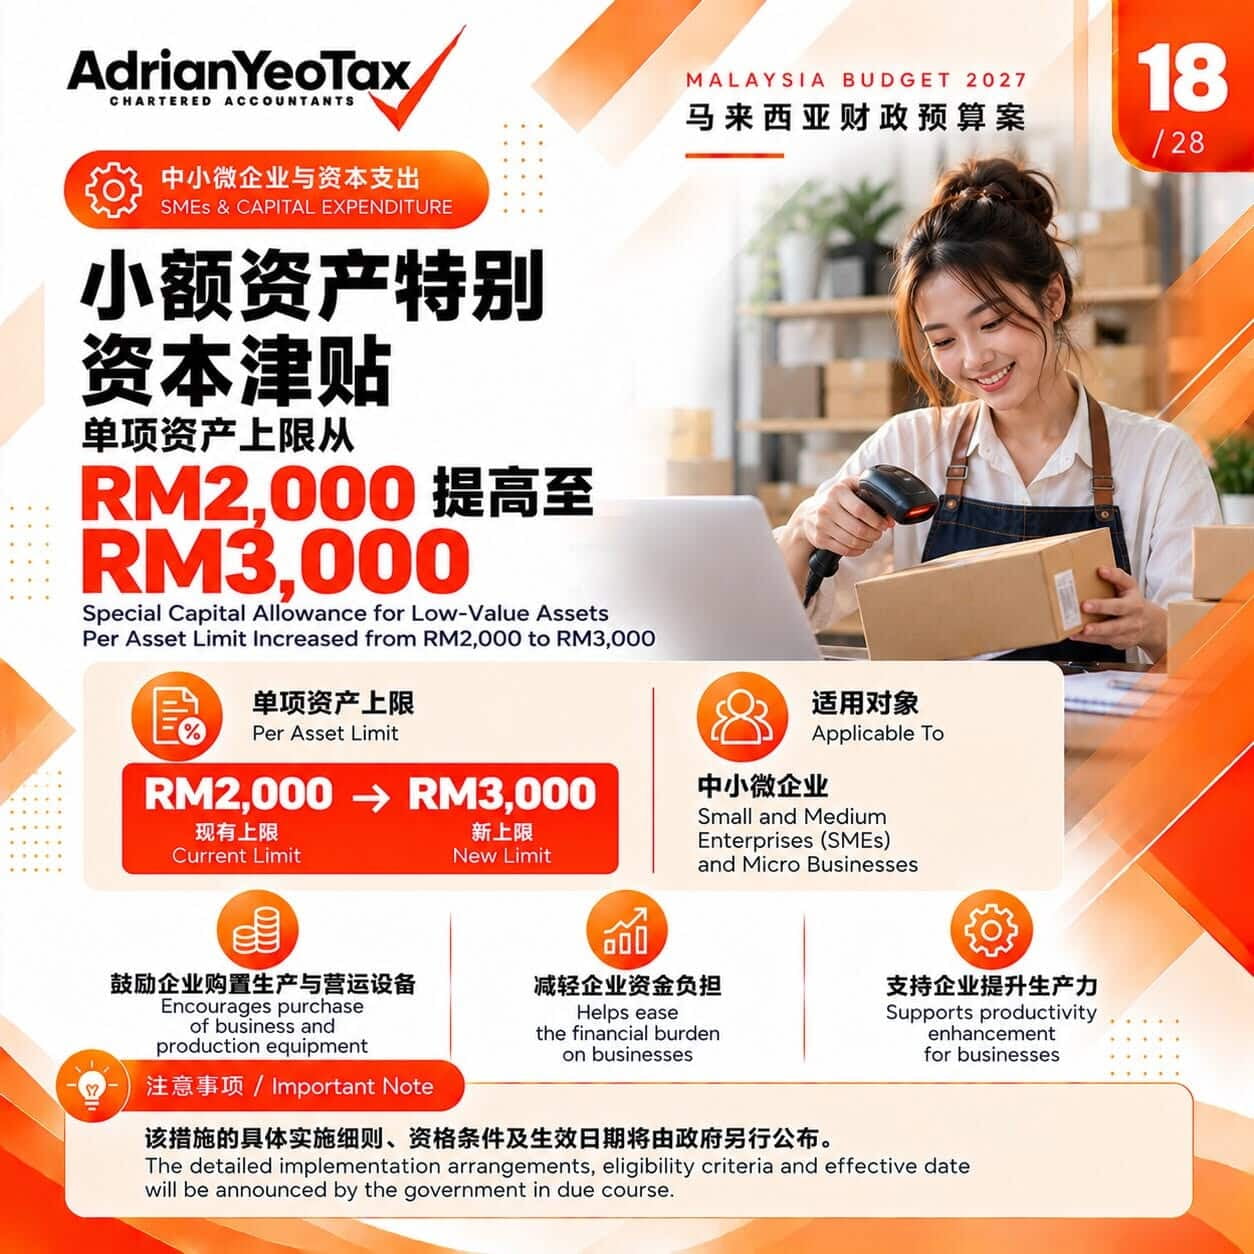
- The cost limit per asset rises from RM2,000 to RM3,000.
- For companies that are not MSMEs, the annual claim limit rises from RM20,000 to RM30,000.
- For MSMEs, there is no annual cap, as before.
How the allowance works
If an eligible asset costs no more than the per-asset limit, you can claim a 100% special capital allowance in the year you incur the expenditure, instead of claiming small amounts over many years. A larger share of your equipment purchases can now qualify for an immediate deduction.
An example
Suppose a business buys a laptop for RM2,800 and a set of office equipment for RM2,500 in 2027. Under the old RM2,000 limit, neither would have qualified for the special allowance, and both would have been claimed under the normal rates, spread across several years. Under the new RM3,000 limit, both can be claimed at 100% in the first year, subject to the other conditions.
The total tax deduction over the life of the asset does not change. The benefit is timing: you get the deduction sooner, which helps cash flow. For a company paying tax at 24%, a RM2,800 asset written off in one year reduces that year’s tax by about RM672. An MSME at the 14% or 16% rate would save less in tax, but still gets the deduction sooner.
MSMEs and larger companies
| Company type | Per-asset limit | Annual claim cap |
|---|---|---|
| MSMEs | RM3,000 (from RM2,000) | None |
| Other companies | RM3,000 (from RM2,000) | RM30,000 (from RM20,000) |
Points to check
- Eligible assets. The allowance is for plant and machinery used in the business. Certain assets, such as those with a very short expected life, are generally excluded.
- Assets that are not eligible. Assets that exceed the limit, or amounts above the annual cap for non-MSMEs, are claimed under the normal capital allowance rates.
- Disposals. If you sell an asset after claiming 100%, a balancing charge may apply, so keep records.
- MSME status. Check whether your company meets the MSME definition, because it decides whether the annual cap applies.
- Guidance to come. LHDN issued a public ruling on small value assets on 30 September 2026, based on the RM2,000 limit. An update reflecting the new threshold is likely.
Related measure: accelerated capital allowance extended
Budget 2027 also extends the accelerated capital allowance for locally purchased plant, machinery and ICT equipment to 31 December 2030. Together with the higher small value asset limit, this makes equipment investment more tax-friendly.
What to do now
- Plan your purchases. If you are planning to buy equipment in 2027, check whether items fall under the RM3,000 threshold.
- Keep an asset register. Record each asset’s cost, date and use, and separate special and normal allowance claims.
- Review your MSME status and your annual spending on small assets.
- Wait for LHDN guidance on the final rules before filing for YA 2027.
Speak to AdrianYeo Tax
Capital allowances can look simple, but the details matter. Our chartered accountants can help you structure purchases and claims, and keep your records ready for LHDN.
This article is for general information only and does not constitute tax advice. Measures are based on Budget 2027 announcements and may change when the legislation is finalised. Please consult a tax professional about your specific circumstances.